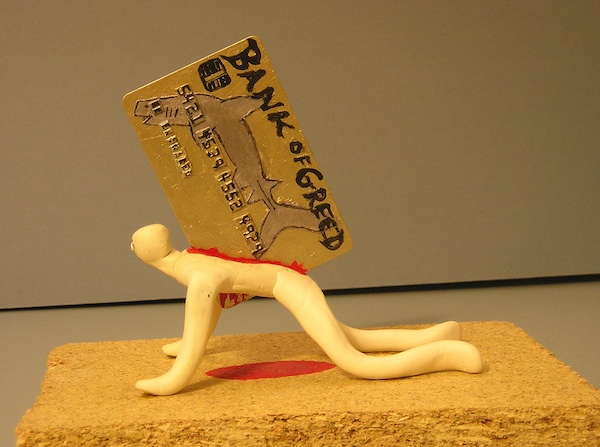
Albert Brenner: ‘Überizing; The Democratizaion of Usury’

When caught in a current, it is always prudent to swim with the current, but to the side – to exit. The great Banking Crisis has, once again, shown that simply swimming with, or against, the current is all for naught. The current of human greed is inexhaustible. Social responsibility is last on the list in the affairs of the unholy alliance between politics and finance. Profit is privatized whilst loss is socialized all with the unashamedly overt support of the democratically elected governments of the West (Iceland being the notable exception).

To be fair; said governments had to intervene to save the System from self-imploding. Quantitative easing saved the day, for today. But what about tomorrow? Giving a drunk more booze sure sooths the longing, but it cannot, be any and all means, cure the addiction.

Marxism tried to “cure” said addiction by fervently advocating for the abolition of private property (read private capital hoarding) thereby hoping to “cold-turkey” the all-too-human need to possess/own. This “cure” obviously failed… due to the imperatives of evolutionary pressures, the dictates of Natural Law and the moral precepts in/of Christianity.

As naively Progressivist as the above endeavour was and still is, in certain countries – the underlying motive to undermine said unholy alliance between politics and finance cannot be shunned outright. Fact is: the common wo/man always has to bear the burden when things go awry among these, hitherto, “powers-that-be”.

But what if modern technology has the potential to, at least, buffer the excesses of the System… to the benefit of the common man who, at the end of the day, actually sustains it? This author believes it is indeed possible to “exit” the System without (it) leading to the self-implosion (thereof).

All that is needed, is the “democratisation” of usury/banking. This is a real possibility, given the incredible advances of, especially, the IT Revolution. This revolution has, inter alia, opened up the incredible (liberating) potential of “non-mediation” – from age-old fixed structures, e.g. monopoly-capitalism.

The first example of “non-mediation” in the IT Age was Napster. This (free) file-sharing platform allowed users the liberty to download and compile their choice of music in a single data storage unit “burnt” CDs, back then. This “non-mediated” liberty to choose (your own music) led directly to the invention of the Apple iPod. And this, as we know, propelled Apple into the dizzying heights of profit unheard of before – a (current) quarterly turnover that equals the total yearly industrial output of Russia.

This process of “non-mediation” has rolled on relentlessly. It simply cannot be stopped. A new Age has dawned. A true revolution. Just last week, taxi drivers in France took to the barricades to protest against the cell-phone app called Über. This simple app directly threatens their livelihood insofar as it turns (every) common man, with a car (and time), into a taxi driver. In short; the monopoly on public transport taxi drivers had, has been broken via the process of “non-mediation”.

So why not apply the same principle to banking? Bankers have, for too long already, monopolised usury. Simply put; why not “Überize” banking especially given the extremely low interest rates offered by banks in the West nowadays?

Just imagine (theoretically) giving every common man the possibility to be a banker. Would that not be a sterling approach to “distribute” (the) wealth equally among those who actually create/d said wealth? Labour topping investment, this time round à la Piketty. Said private citizens could then, when vetted accordingly, truly be the banker. There would, obviously, be many “loan-sharking” pitfalls. But then; if properly regulated, it would certainly allow the common man to participate more directly in the financial system more than ever before!

It obvious that the common man does not have the funds/savings to act as the guarantor/financier of the 30-year mortgage plan of his/her neighbour But if (the) like-minded team up for the common purpose of taking social responsibility for the private financial decisions of the individual, this could be overcome without too much ado. It is simply a question of trust… among the like-minded.

It is indeed impossible to swim against the tide of human greed. But it is also not impossible to swim to the side, to the benefit of your neighbour who, at the end of the day, means you. Or do you want to be the sorry sucker who always picks up the tab every time the banker and his/her politician buddy profit whilst socialising loss… eternally at your expense?

I say NO!

Ergo, exit… by Überizing Usury.

Russia’s two largest banks plan SWIFT alternative

The two biggest banks in Russia, Sberbank and VTB, are in talks to create an alternative to the SWIFT global system for interbank financial communications, VTB head Andrey Kostin said.

According to Kostin, Russia has two options: either use the system run by the Russian Central Bank or create a new homegrown transaction platform.

“There is an alternative, we can use the Central Bank system that is already in operation, and we may make our own, we are already in discussions with Sberbank,” Kostin told reporters in Washington DC, where he is for the annual fall meetings of the International Monetary Fund (IMF) and World Bank.

However, the catch with the Central Bank’s international transaction system is the price.

“It’s expensive, in fact several times more expensive than the SWIFT payment system,” the VTB head said.

“If we create our own interbank system, which isn’t difficult at all and we are in the process of doing, it will be cheaper. And then hold talks with the Central Bank,” Kostin said.

Switching Russia off SWIFT, the Society for Worldwide Interbank Financial Telecommunication, would instantly isolate it from global finance, as happened with Iran in 2012. According to reports, EU leaders, especially in Britain, were discussing the option as a sort of super sanctions to punish Russia for its involvement in the Ukraine crisis. Many US senators have also been pushing to block Russia from SWIFT payments.

SWIFT, the Brussels-based global payments system, said last week that they wouldn’t succumb to political pressure and cut Russian payments and would continue services. The group said that disconnecting Russia violates the company’s mission and that it doesn’t make such unilateral decisions.
However because it’s based in Brussels, it would have to comply with any greater EU ruling.

Last month the SWIFT system transmitted more than 21 million financial messages a day between more than 10,500 financial institutions and corporations in 215 countries.

The Russian National SWIFT Association, or ROSSWIFT for short, is the second biggest worldwide, after the US.

Source: RT

US mortgage applications remain weak despite rising home prices

Fierce bidding wars for homes in the nation’s capital are slashing applications from borrowers interested in taking out a purchase mortgage, an industry group said Wednesday.

Around the country, rising mortgage rates over the past year have cut applications for loans to buy a home, with the latest weekly reading on a U.S. gauge from the Mortgage Bankers Association showing a 5% drop from the prior week (as seen in the chart). But in hot markets like Washington, where there’s a low supply of homesavailable for sale and borrowers  haven’t been put off by pricier loans, would-be mortgage applicants are still giving up on borrowing.

“Some lenders continue to report that they have pre-approved borrowers who have been unable to find a property given the tight inventory in certain markets,” said Mike Fratantoni, MBA’s chief economist.

Just how hot is D.C.’s market? More than one-quarter of homes sold in May closed above their list price, according to Redfin, a real estate firm. But that statistic pales in comparison to the scorching markets in San Jose and San Francisco, where almost 70% of homes sold above their asking price.

Elsewhere in the country, rising rates are taking a toll on loan applications from borrowers who have become priced out of the market. Plus, borrowers still face the extremely high standards that lenders erected in the wake of the financial crisis.

Source: WSJ

Goldman Sachs profits double on investment gains, lower tax rate

Goldman Sachs Group Inc (GS.N) said quarterly profit doubled, boosted by investment gains and a lower tax rate.

Lower taxes help Goldman Sachs

Goldman’s investing and lending segment, which tracks its investments in private equity deals, publicly traded stocks, loans and bonds, produced nearly seven times as much revenue in the second quarter as in the same period last year, much more than analysts expected.

Investors questioned how much revenue growth the bank can generate by investing its own capital under new regulations. The Volcker rule, part of the 2010 Dodd-Frank financial reform law, limits banks’ market wagers with their own money. But the industry has years to comply with the law, and Goldman believes most of its investing and lending activities already do.

Goldman’s effective tax rate dropped to 27 percent from 32 percent in part because the bank is electing to keep more of its international income permanently offshore, and because it earned more money overseas. Chief Financial Officer Harvey Schwartz told analysts on a conference call that the lower tax rate was not likely to be repeated.

“It’s tough to get too excited about these numbers because they’re potentially unsustainable,” said Tom Jalics, senior research analyst at Key Private Bank, whose clients own bank shares.

The results underscore the difficulties Goldman and its rivals face in navigating the post-crisis world. With regulators pressing banks to boost capital levels, many of Goldman’s most profitable businesses are earning less. The bank’s return on equity, a measure of how effectively it wrings profit from shareholders’ money, was just 10.5 percent in the second quarter, a hair above what it would pay for equity funding.

Overall, Goldman’s net income rose to $1.86 billion, or $3.70 per share, in the quarter, from $927 million, or $1.78 per share, a year earlier.

Analysts on average had expected $2.82 per share, according to Thomson Reuters I/B/E/S.

Net revenue rose 30 percent to $8.61 billion.

The biggest contributor to revenue was fixed income, currency and commodities (FICC) trading, which reflects trading with clients. Revenue there rose 12 percent to $2.46 billion.

Goldman’s results echoed similar trends in the investment banking units of JPMorgan Chase & Co (JPM.N) and Citigroup Inc (C.N), whose fixed-income trading businesses also benefited from improvements in trading and underwriting revenue in the second quarter. – Reuters