Gold prices up

Gold was up $42.70 per ounce in trading today.

The New York spot price was $1,320.20

Also on Wall Street, investors remained in a record-setting mood Thursday.

The Standard & Poor’s 500 index closed at an all-time high for the second time in two days and notched its fifth gain in five days.

The Dow Jones industrial average and Nasdaq composite ended mixed after drifting between small gains and losses for much of the day.

The three key stock indexes all opened higher, holding on to tiny gains in premarket trading as investors sized up the latest data on unemployment aid applications and an index of economic indicators.

The Labor Department reported that applications for unemployment benefits fell last week to 312,000, the lowest in more than six years. The Conference Board added to the good news, saying its index of leading indicators rose 0.5 percent in May from the previous month.

The market began to drift lower, however, as investors looked beyond the economic data and focused instead on a mixed bag of corporate earnings from companies such as Kroger, Rite Aid and Pier 1 Imports.

By midday, stocks veered into the red, where they remained until halfway through the final hour of trading, when a late push elevated the S&P 500 and Dow barely higher on the day.

The S&P 500 index rose 2.50 points, or 0.1 percent, to 1,959.48. That’s slightly above the prior day’s record close of 1,956.98. The last time the index closed at a record high was June 9th.

The Dow Jones industrial average added 14.84 points, or 0.1 percent, to 16,921.46. The Nasdaq composite slipped 3.51 points, or 0.1 percent, to 4,359.33.

The three indexes are all up for the year.

The U.S. economy shrank at an annual rate of 1 percent in the January-March quarter, the victim of a severe winter which slowed business activity in a number of areas. Many analysts anticipate growth rebounded strongly in the April-June quarter.

The market will get a sense of that next month, when the next round of corporate earnings begins. Until then, the next key market mover will likely be the June jobs report, due out the first week of July.

Bond prices fell, sending the yield on the 10-year Treasury note up to 2.63 percent from 2.59 percent late Wednesday.

Source: Elko Daily Free Press
Gold rises sharply on Fed interest-rate outlook

Gold futures jumped the most in 14 weeks as the Federal Reserve said U.S. interest rates will remain low, driving the dollar lower and boosting demand for the precious metal as an alternative investment.

According to Bloomberg, the greenback fell to a four-week low against a basket of 10 major currencies. Yesterday, Fed Chair Janet Yellen said rates will probably remain low for a considerable time after debt purchases by the central bank end. In 2013, gold ended a 12-year rally on expectations that the Feb would taper monetary stimulus following gains in the labor market.

“Some people are buying gold since Yellen made it clear that the low-interest rate regime is here to stay,” Tommy Capalbo, a broker at Newedge Group in New York, said in a telephone interview. “The dollar’s weakness is also supportive.”

Gold futures for August delivery rose 1.7 percent to $1,294.60 an ounce at 10:05 a.m. on the Comex in New York, A close at that price would mark the biggest gain for a most-active contract since March 12. Earlier, the metal reached $1,295.90, the highest since May 23.

The modern economy depends on 60+ obscure metals

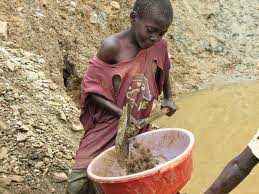
Mining coltan
Mining coltan

Over half a century ago, the global economy largely depended on just ten or so different materials. Most important products were made out of wood, brick, iron, copper, gold, silver or a few plastics — and that was about it.

Things are wildly different today. A huge chunk of modern-day technology, from hybrid cars to iPhones to flat-screen TVs to radiation screens, use dozens of different metals and alloys. A computer chip typically involves more than 60 different elements that are specifically selected to optimize performance, like europium or dysprosium.

And that’s long raised a concern: What would happen if we run short of any of these valuable metals? Say there’s a war. Or unrest in a crucial mining region. Or China decides to lock up its strontium deposits. Could we easily come up with substitutes? Or is modern society vulnerable to a materials shortage?

Here’s the case for vulnerability: A fascinating recent paper in The Proceedings of the National Academies of Science looks at 62 different metals that are widely used in modern-day industry. For a dozen metals, potential substitutes are either inadequate or flat-out unavailable. And there are no “excellent” substitutes for any of the 62 metals. A shortage of any of them could do some damage.

Read more.

South Africa’s Zuma equates mine layoffs with ‘blackmail’

South African President Jacob Zuma said on Monday that mining companies were almost engaging in “blackmail” when they announce plans to close mines and lay off workers.

Zuma’s pre-recorded comments broadcast on CNBC Africa come as the government, unions and ruling African National Congress have come out strongly against proposals by Anglo American Platinum (Amplats) to mothball two mines and lay off 14,000 workers as it strives to return to profit.

“When the miners say we are cutting down, we are closing … You see, that is almost blackmail,” Zuma said.

Zuma also said “lower wages in the mining industry has led us into trouble.”

South Africa’s platinum and gold sectors were rocked last year by violent strikes and labour violence that killed over 50 people and hit output.

Amplats, the world’s top platinum producer, said on Monday it had made its first annual loss last year because of the strikes and warned of growing labour unrest.

Zuma’s remarks coincide with an investor conference on mining in Africa being held this week in Cape Town.

Separately, Mines Minister Susan Shabangu told the conference proposals by the ruling ANC to introduce a “resource tax” would be carried out with an intent to keep South Africa competitive among other major mining countries.

“We’ve got to compete with Australia and Canada. So if there are any taxes which must be implemented we must be mindful,” she said. – Reuters

The race for resources

The year 2030 will see an increasingly chaotic world where China is the top economy and demand soars for resources, a US intelligence report said Monday.

The National Intelligence Council, in its first assessment in four years aimed at shaping US strategic thinking, said that China will surpass the United States as the largest economy in the 2020s, in line with independent forecasts.

But the study said that the United States, while weaker, will probably stay the top player in two decades thanks to its role in resolving global crises, its technological prowess and its “soft power” that attracts outsiders.

“The US most likely will remain ‘first among equals’ among the other great powers in 2030 because of its preeminence across a range of power dimensions and legacies of its leadership role,” the 137-page report said.

“Nevertheless, with the rapid rise of other countries, the ‘unipolar moment’ is over and Pax Americana — the era of American ascendancy in international politics that began in 1945 — is fast winding down,” it said.

The study predicted that Asia’s economy, military spending and technological investment would surpass those of North America and Europe combined by 2030, but warned of major uncertainty over an emerging China.

“If Beijing fails to transition to a more sustainable, innovation-based economic model, it will remain a top-tier player in Asia, but the influence surrounding what has been a remarkable ascendance will dissipate,” it said.

China’s global power is likely to keep rising but at a slower rate — a phenomenon of easing growth that, according to historical precedent, makes countries “likely to become fearful and more assertive,” the study said.

Europe, Japan and Russia are expected to maintain slow economic declines through 2030, while a number of middle-tier countries could rise such as Colombia, Egypt, Indonesia, Iran, Mexico, South Africa and Turkey, it said.

The study expected major benefits from technology by 2030, but warned that climate change threatened to pose serious challenges.

With a growing population and rising incomes, the planet’s demand for water, food and energy will grow by 35, 40 and 50 percent respectively by 2030, it said.

A wealthier China and India will likely need to rely more on food imports, driving up international prices. Families in low-income nations would feel the pinch hardest on food, likely fueling social discontent.

The National Intelligence Council estimated that the world would have nearly 8.3 billion people in 2030, up from 7.1 billion now, but that the average age would be older — with potentially giant consequences.

The study said that 80 percent of armed and ethnic conflicts occurred in nations with youthful populations. The number of youthful states will fall significantly by 2030, with the remaining ones clustered around central Africa.

Other areas that will still have youthful populations — and the fuel for potential conflict — include Afghanistan, western and tribal areas of Pakistan and India’s poorer northern states of Bihar and Uttar Pradesh, it said.

By contrast, the study found that the Middle East “will be a very different place” in 2030 with the gradual aging of the youth bulge that took to the streets in the Arab Spring protests that brought down autocratic leaders.

But the report predicted instability in nations with rooted sectarian or other tensions such as Bahrain, Iraq, Libya and Syria along with Yemen, which the study predicted could break up for the second time.

Iran was a question mark. The study expected “far-reaching instability” if Iran developed a nuclear weapon, but also said that a more pro-Western Iran could emerge due to public pressure and infighting within the clerical regime.

The study said a potential resolution to the Israeli-Palestinian conflict would have “dramatic consequences,” but suggested that a more likely scenario consisted of unofficial actions that lead toward a Palestinian state with key issues such as the status of Jerusalem remaining unresolved in 2030.

While the study looked at trends, it warned of the potential for game-changing events by 2030 such as a global economic meltdown. – AFP

Gold-digging in Paris

Last week, police in the French capital arrested three people as part of a widening grave robbery investigation.

There was further public outrage after two masked intruders shot dead a 52-year old precious metal worker when he tried to stop them stealing gold from his foundry in the chic central Parisian district of Le Marais.

Police said sky-high market prices for precious metals are acting as a magnet for thieves with scant regard for the living or the dead.

In Pantin cemetery, in the north of Paris, dozens of bodies have recently been dug up, with gold teeth and jewellery stolen from them.

Police sources said the three men seized last week were gravediggers employed by the city’s cemeteries.

Last month, four other men – three from the same Pantin cemetery – were arrested and placed under investigation for aggravated theft, grave robbery and violating the integrity of a corpse.

According to a source close to the investigation, the men removed personal belongings from corpses in the freshest graves, opening them in the dead of night.

Two of the men were caught wearing miner’s helmets and gloves. Their boots were covered in fresh earth.

One of the suspects was found to be carrying 10 gold teeth.

After the initial arrests, the mayor of Paris, Bernard Delanoe, expressed his outrage and ordered the city authorities to step up surveillance of cemeteries.

Even closer to the city centre, a metalworker was gunned down last Wednesday when he fought back against motorbike helmet-clad thieves trying to break into the gold workshop where had been employed for 36 years.

A neighbour said she heard him shout: “I haven’t got the keys!” before chasing the attackers and being shot.

Visiting the scene shortly after the murder, Manuel Valls, the interior minister, admitted: “There is a problem with regulating gold, with illegal workshops that recycle gold, which is often the product of theft or snatched gold chains.”

Precious metal theft is big business is France. Earlier this year, the national rail operator, SNCF, launched a special security programme to clamp down on the massive theft of copper cables that has led to huge delays on its lines.

Ten days ago, his men broke an illicit gold reseller network operating out of the Saint Denis train station in a northern Paris suburb. “It was a real open supermarket for stolen gold. All the thieves from across the capital came there to sell their wares for cash,” he told The Daily Telegraph.

He said a large part of their booty ended up in Belgium, where “legislation is more relaxed”. – The Daily Telegraph