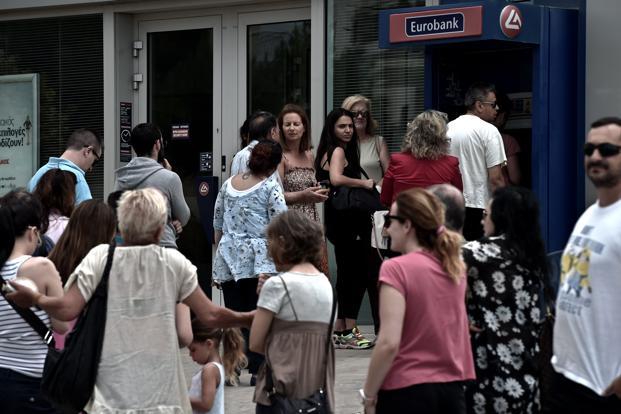
Greek crisis ignites

Banks in Greece and the country’s stock exchange will be shut all week in a sign of the deepening financial crisis.

The drastic move comes after people rushed to withdraw their cash amid panic ahead of the referendum on bailout terms.

Under the controls, there will be a daily €60 limit on withdrawals from cash machines, which will reopen on Tuesday.

The Foreign Office has warned British tourists to take enough cash to cover emergencies in case cash machines are emptied.

It said: “Visitors to Greece should be aware of the possibility that banking services – including credit card processing and servicing of ATMs – throughout Greece could potentially become limited at short notice.”

The euro fell sharply against the dollar amid investor jitters of a Greek debt default and exit from the eurozone.

Speaking in a televised address, Prime Minister Alexis Tsipras urged calm and insisted bank deposits were safe.

He blamed European partners and the European Central Bank for forcing Greece’s hand.

And he said the latest developments would not halt the planned referendum next Sunday.

But queues at petrol stations and the declining number of bank machines still dispensing cash underlined the scale of the country’s economic plight.

European creditors have refused a request to extend Greece’s international bailout beyond Tuesday, until after the referendum.

Source: Skynews

Greece misses deficit target as bailout deadline looms

Cash-strapped Greece fell well short of its budget deficit reduction targets last year, official figures showed Wednesday in a development that’s likely to add pressure on the radical left-led government during tortuous talks with bailout creditors.

The country’s statistical authority said the 2014 deficit was 3.5 percent of Greece’s annual GDP, considerably higher than the 0.8 percent forecast. And after stripping out the cost of servicing Greece’s crippling public debt, a modest primary surplus of 0.4 percent was recorded — short of the 2 percent target.

The new government elected Jan. 25 had already said the shortfall would be bigger than expected. But the official confirmation comes at a time Greece is negotiating a long-delayed rescue loan installment, without which it will run out of cash.

Greece is unable to tap the international bond market for funds due to sky-high borrowing rates, which reflect a lack of confidence in the country being able to repay its debts. Greek stocks closed 1.9 percent down Wednesday, another sign that investors in the country are jittery.

Greece has been surviving on rescue loans from its European partners and the International Monetary Fund since mid-2010, and the new government won a four-month extension to the main, European part of its bailout in February.

Under the extension agreement, Athens must present a series of economic reform measures that meet the approval of its creditors. Authorities are hoping for a final agreement next week, when all 19 finance ministers from the eurozone countries, including Greece’s Yanis Varoufakis, meet on April 24 in the Latvian capital of Riga.

But several European officials have raised doubts about the possibility of a deal then. Greece has some big repayments coming up over the next few months and without the rest of its bailout cash, the country could be staring at a possible default and an exit from the euro.

Source: eNCA

‘US plans to assassinate me’

The President of Argentina has suggested that the United States are planning to overthrow her government, and even assassinate her on Tuesday evening.

After last week’s alleged threats on her life by Islamic State connected militants, Fernandez said, “So, if something happens to me, don’t look to the Mideast, look north,” she declared at the Government House.

She added in her two hour long speech that the United States “are firing missiles at the Middle East … but they won’t fire missiles on Argentina, they are sending financial and speculative attacks.”

The President also characterized a recent warning about crime that the U.S. Embassy sent to its citizens in Argentina as a “provocation.”

During her address to the nation, she said of the United States Judge Thomas Griesa’s decision to find Argentina in contempt of court that, “It’s naive to think that this (decision) is merely the work of a senile judge”.

Fernandez did not leave the local Argentine financiers, saying that there are those “among us who conspire with the vulture funds.”

She revealed that, “We’re going to impose stricter controls, we’re going to demand the central bank and regulators apply the law in all its terms.”

She accused the wealthy of the nation and overseas capital wanting a “return to the past, when Argentina was on its knees begging for money at exorbitant interest rates.”

“In the nineties Argentina supposedly was the best of the class for the multilateral organizations, but it was all a castle of cards and when it all collapsed, instead of helping out they came running to recover their money.”

She ended by calling on all of her supporters to be “united and prevent Argentina from falling into the hands of those who want a return to conditions of the past: the vulture funds and even worse their conspiring allies among us, who want to see Argentina indebted, helplessly at the mercy of speculators.”

Source: TeleSur

China, Argentina agree on currency swap

Argentina, which defaulted on its debt in July, will receive the first tranche of a multi-billion dollar currency swap operation with China’s central bank before the end of this year, the South American country’s La Nacion newspaper reported on Sunday.

The swap will allow Argentina to bolster its foreign reserves or pay for Chinese imports with the yuan currency at a time weak export revenues and an ailing currency have put the Latin American nation’s foreign reserves under intense pressure.

La Nacion said Argentina would receive yuan worth $1 billion by the end of 2014, the first payment of a loan worth a total $11 billion signed by Argentina’s President Cristina Fernandez and her Chinese counterpart in July.

The daily newspaper said the presidents of the countries’ two central banks had met on the sidelines of a meeting in Switzerland, but did not say how it had obtained the information.

Fernandez’s government has imposed stringent import and capital controls to safeguard the dwindling reserves, now at around eight-year lows, which it needs to pay its debts.

Source: Reuters

What happened in Argentina

Vulture funds buy insolvent debts for a song and later try to cash in on them by force. Billionaire Paul Singer has made it his specialty. Today he is intent on consolidating his fortune at the expense of the Argentinian people, while already setting his sights on Spain

By Jérome Duval, Fatima Fafatale.

The vulture fund NML Capital that, together with others, has Argentina on the edge of suspending payments, is already devouring the rotting flesh of the Spanish market. Elliott Management, the opportunistic fund of the serial U.S. speculator Paul Singer, has already pocketed a billion euros of Bankia’s failed credit and 300 million euros of Santander. It is estimated that it has paid hardly 50 million for both these portfolios, according to Auraree.com.

In March 2013, the Spanish financial press informed that Elliott had acquired from the Santander Group a portfolio of 300 million euros of defaulting credit of Santander Consumer Finance with a discount approaching 96%. The price that was paid was laughable: about 12 million euros, according to Cinco Dias.

Elliott had acquired from the Santander Group a portfolio of 300 million euros as defaulting consumer credit of Santander Consumer Finance.

In August of the same year, 2013, Bankia, the nationalised entity that most benefited from the rescue of the Spanish banks, which had considerably raised the public debt, informed that three portfolios of bad credit had been sold for a total debt volume of 1,353.9 million euros. In the relevant communication to the CNMV (National Stock Market Commission), it was not mentioned to whom the loans had been sold to or at what price. Despite the evident lack of transparency, the financial press has put names and numbers to the operation, which it is estimated “may have a discount of 95%”. The buyers of the three portfolios were the vulture fund Cerberus, which is advised by José Maria Aznar Jr, the son of the former President, Elliott and the Norwegian recovery business, Lindorff. “The portfolio was valued at 1,354 million but only forked out 68,” according to Finanzas.com. We have been in contact with Bankia for confirmation from the other side and its response has been that “for confidentiality” they never give the number and “the buyers who do not want to be identified”.

A few months later, it emerged that Elliott bought the household debt recovery firm Gesif to convert it into his operational base for the Spanish market. Its director-general was Melania Sebastián, who was in charge of information management at the Banca Comercial de Caja Madrid, who will continue with the moneylenders of Gesif. It is worth noting how a former director of Caja Madrid acts as the intermediary between the nationalised Bankia and Elliott’s vulture fund.

What happened in Argentina

The vulture funds make money taking advantage of countries in difficulties, like Argentina during the crisis of 2001, to buy debts cheap. Later they wait for an opportune moment to oblige them to buy them back at a much higher price with court orders, including deferred interests and judicial costs.

This is how they speculate on public debts, endangering the social spending that benefits the great majority of the population. These vultures went for lawsuits after having refused to form a part of the 93% of creditors who accepted the exchange with the government. Now the New York district judge, Thomas Griesa, has prioritised the payment of the vulture funds, which opens the door to an avalanche of demands that could result in the suspension of payments in Argentina on July 30. As Julio C. Gambina puts it so well, “nobody precisely knows where the demands of the creditors could reach of the unpayable debt”, but we know that the cost for the Argentinean people could be catastrophic.

Who are behind these vulture funds? NML Capital is a subsidiary of the inversion fund, Elliott Management Corporation, registered in the fiscal paradise Cayman Islands. It is the empire of Paul Singer, the multimillionaire champion of the gay rights and neo-conservative aggression.

Elliott speculates, among other things, with public debts, violating the sovereignty of the states and its peoples. But he also speculates with private debts and in 2011 came to possess two million dollars of Lehman Brothers.

Singer was the major financier of the presidential campaign of George W. Bush in 2004; he also contributed to Mitt Romney’s campaign in 2012 and to that of the New York mayor, Rudolph Giuliani. Moreover, he is the major private financier of the New York police. As one of the principal financiers of the Republican Party, he plays an important part in the U.S. politics and, therefore, also in international politics.

The foundation that bears his name, The Paul E. Singer Foundation, praises him for his philanthropy, his leadership in the expansion of free trade, his contribution to U.S. national security and the “future of Israel”. Moreover, Singer is president of the Manhattan Institute for Policy Research.

The frigate is not for handing over or for sale

Regarding the Argentinean case, NML is the principal financier of the organisation, American Task Force Argentina (AFTA), a lobby that influences the Congress and the U.S. justice, harming Argentina. To give ourselves an idea of the power of these vultures, NML could even embargo the Argentinean frigate, Liberty, in Ghana in October 2012, demanding the Argentinean state for about $370 million for unpaid bonds.

Enough of vultures: Argentina united for a national cause

What is happening in Argentina is emblematic of what Greece is starting to feel where vultures like Dart Management operate, with its headquarters in Cayman Island and which also operates in Latin American countries. In 1999, NML achieved, through a ruling in the United States, the payment from Peru of $58 million for a debt that the fund had bought for $11 million. It also did business with the Democratic Republic of Congo.

Source: voltairenet.org

Chase Bank limits cash withdrawals

chaseIn March 1985 when Chase Manhattan Bank led a string of banks to the South African Reserve Bank and demanded their money back, the economic pressure on South Africa intensified dramatically. Some speculate that Chase’s move was what really pulled the rug out from under the Afrikaner government.

Threats of disinvestment were loud and insistent then and companies from Kodak, to Mobil and Barclays bank started to withdraw from South Africa.

Today the same bank, responsible for the rape and looting of South Africa, Chase Bank, has moved to limit cash withdrawals while banning business customers from sending international wire transfers from November 17 onwards, prompting speculation that the bank is preparing for a looming financial crisis in the United States.

Numerous business customers with Chase BusinessSelect Checking and Chase BusinessClassic accounts have received letters over the past week informing them that cash activity (both deposits and withdrawals) will be limited to a $50,000 total per statement cycle from November 17 onwards.

The letter reads;

Dear Business Customer,

Starting November 17, 2013:

– You will no longer be able to send international wire transfers. You will still be able to send domestic wires and receive both domestic and international wires. We’ll cancel any international wire transfers, including reccurring ones, you scheduled to be sent after this date.

– Your cash activity limit for these accounts(s) will be $50,000 per statement cycle, per account. Cash activity is the combined total of cash deposits made at branches, night drops and ATMs and cash withdrawals made at branches (including purchases of money orders) and ATMs.

These changes will help us more effectively manage the risks involved with these types of transactions.

Another letter received by Peak to Peak Charter School, a college in Colorado, states that the option to send both international and domestic wire transfers has been withdrawn from Chase business savings account holders.

Other Chase business customers confirmed they had also received similar or identical letters.

“I’m a Chase customer with both of the type accounts mentioned and got the letter posted,” wrote one.

“I have been a loyal customer of Chase for 11 years and I received the letter for my business and when I called about this I was told basically piss off and find another bank!” added another.

Chase is obviously very keen to make it hard for their customers to have any kind of control over their savings and is trying to prevent them from sending dollars abroad, prompting concerns that Cyprus-style account gouging could occur in America.

The move to limit deposits and withdrawals while banning international wire transfers altogether is a bizarre policy and will cripple many small and medium-sized businesses with Chase accounts. Buying stock from abroad in any kind of quantity will now become impossible for many companies, while paying employees will also be a headache.

Why has Chase announced such a ludicrous and restrictive policy change and is it related to the potential for a US debt default?

Speculation is rife that the bank is preparing for some kind of economic crisis by “locking down” its customers’ money. Although most still expect a deal to be struck to prevent a US debt default, its impact would “shake financial markets to a degree not seen since the Great Depression,” according to experts.

Others fear the move to restrict international wire transfers is part of a plan to protect against a near-future collapse of the US dollar.

Whatever the truth behind the policy change, Chase really needs to publicly explain its reasoning in order to quell the speculation.

The bank’s reputation was already under scrutiny after an incident earlier this year where Chase Bank customers across the country attempted to withdraw cash from ATMs only to see that their account balance had been reduced to zero. The problem, which Chase attributed to a technical glitch, lasted for hours before it was fixed, prompting panic from some customers.

Earlier this month it was also reported that two of the biggest banks in America were stuffing their ATMs with 20-30 per cent more cash than usual in order to head off a potential bank run if the US defaults on its debt. – praag/prisonplanet.com